
Destin Condos for Sale: The Complete 2026 Buyer's Guide
A 2026 buyer guide to Destin condos for sale: submarkets, Gulf-front versus harbor-front, HOA documents, costs, and rental rules.

On this page
On this page
Most advice on Destin condos for sale is too shallow to help you make a smart acquisition. Price, photos, and beach proximity don't tell you what matters most, which building will preserve lifestyle value and produce acceptable net income after HOA, insurance, management, and compliance friction.
Destin earns attention because buyers want direct Gulf access and quick access to the East Pass, HarborWalk, and Crab Island. But buying well here requires more than scrolling listings. It requires building-level underwriting.
Table of Contents
- Why Most Destin Condo Searches Fail Investors
- Decoding Destin's Core Condo Submarkets
- Gulf Front vs Harbor Front A Strategic Analysis
- The Investor's Underwriting Model for Destin Condos
- Navigating HOA Rules and Short Term Rental Regulations
- Advanced Investment and Financing Considerations
- Your Acquisition Framework for a Destin Condo
Why Most Destin Condo Searches Fail Investors
The biggest mistake buyers make is treating a Destin condo like a commodity. It isn't. Two units with similar square footage and similar views can produce very different results because one building is friendlier to short-term rentals, one has weaker reserves, one is exposed to higher insurance pressure, and one has rules that choke revenue.
Most portal searches flatten critical differences. They reward what photographs well, not what underwrites well. A polished listing at a resort-style building may still be the wrong asset if the HOA economics are weak or the rental structure is restrictive.
Practical rule: Never rank Destin condos by asking price first. Rank them by usable income profile, building governance, insurance exposure, and exit liquidity.
If you're starting broadly, use a city-level search like the Dream Destin Realty home search portal to get market visibility, then narrow aggressively by building. That's where the intensive work starts.
Listings don't show the real investment calculus
A listing usually tells you the view, the finishes, and maybe the amenity package. It rarely tells you:
- Rental friction: Whether the association has policies that limit owner flexibility, guest use, or marketing options.
- Cost drag: Whether HOA dues and insurance pressure will erode the income story.
- Assessment risk: Whether deferred maintenance or reserve weakness may force future capital calls.
- Buyer profile at resale: Whether your future exit depends on investors, second-home buyers, or owner-occupants.
A serious buyer should think in terms of net performance and future optionality, not "Can I see the water from the balcony?"
Destin rewards precision
In Destin, lifestyle utility and short-term rental appeal can coexist in the same asset, but confirm that the specific building allows both before assuming it does. You can own near the beach, use the property personally, and still maintain a disciplined investment thesis. But you only get that outcome if you buy the right building in the right pocket of the city.
That's why generic condo advice fails here. Destin is a building-by-building market.
Decoding Destin's Core Condo Submarkets
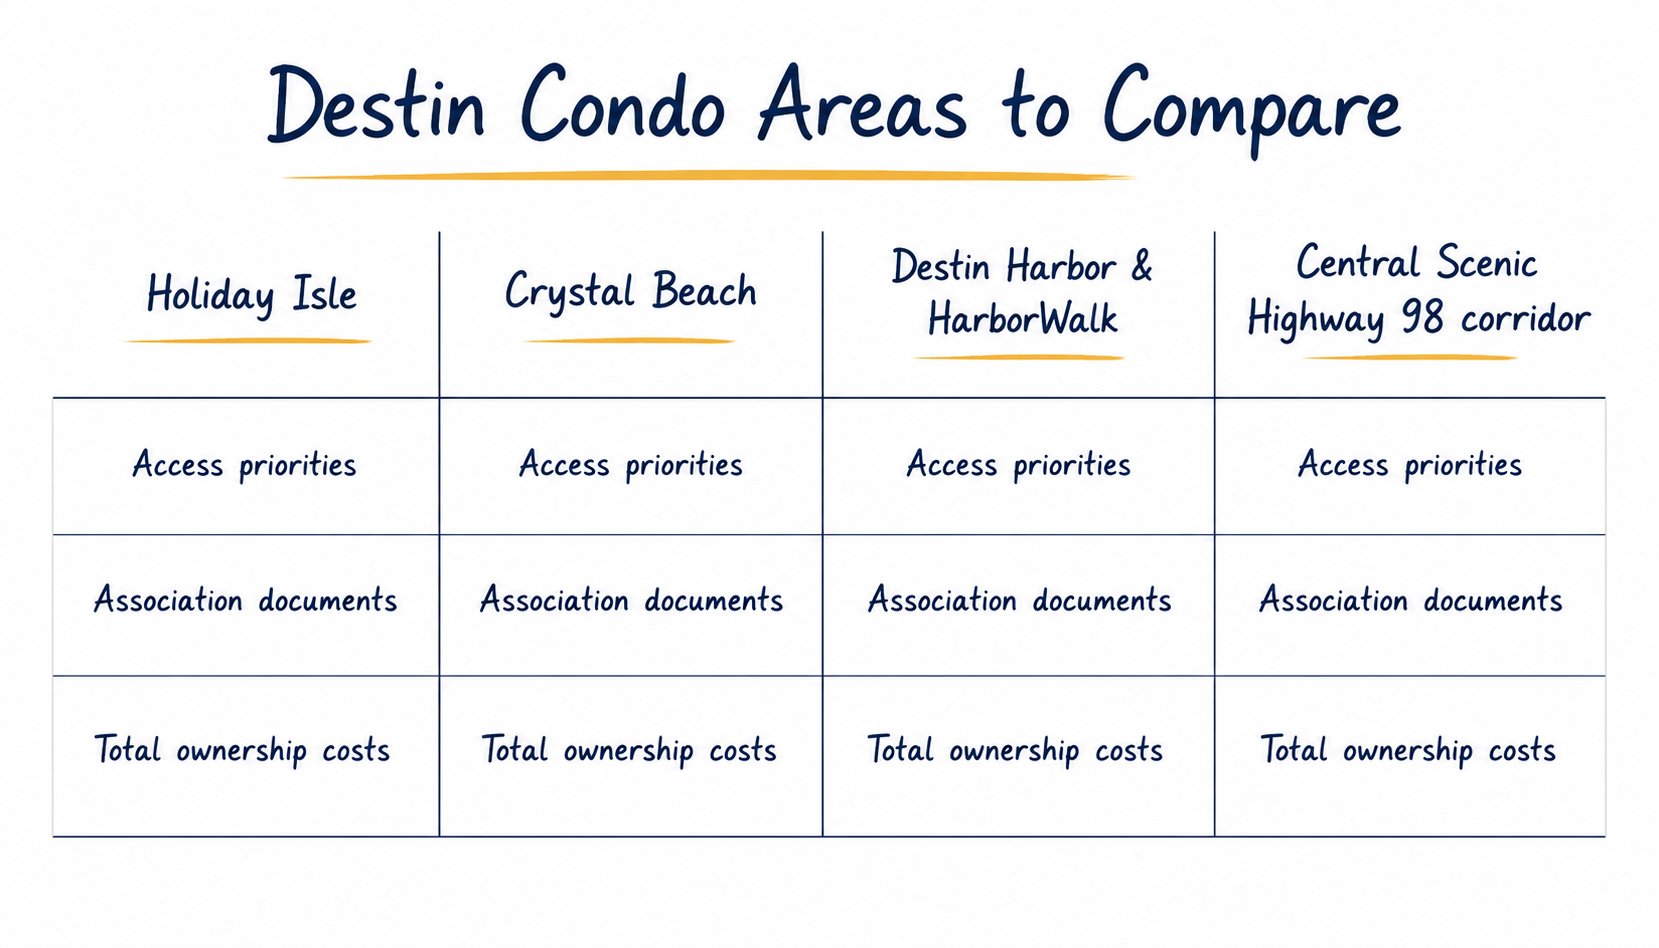
Destin condo inventory isn't one uniform pool. Holiday Isle attracts a different buyer than HarborWalk. Crystal Beach behaves differently than the central Gulf-front corridor along Scenic Highway 98. If you don't separate the city into submarkets, you're comparing unlike assets.
For a broader view of the citywide inventory, start with Destin property searches across the market.
Holiday Isle
Holiday Isle fits buyers who value a quieter setting, boating culture, and fast access to the East Pass. This area tends to attract buyers who want more than beach exposure alone. They want a location that feels tied to Destin's marine identity.
Buildings like Jetty East Condos and Holiday Isle condos are useful examples because they place you in one of the city's most established condo zones. For second-home buyers, Holiday Isle often feels more private than the busier resort-style stretches. For investors, the question isn't whether guests like the location. They do. The question is whether the building's rules and cost structure support your strategy.
Crystal Beach
Crystal Beach has a different profile. It appeals to buyers who care about neighborhood feel, beach access, and proximity to restaurants and retail without the harbor atmosphere. The condo stock here intersects with a broader residential setting, which changes the use case.
This submarket is often better suited to buyers who prioritize lifestyle and selective rental use over pure high-volume vacation-rental turnover.
Nearby Crystal Beach communities with houses rather than condos include Shores of Crystal Beach and Villages of Crystal Beach. Those aren't interchangeable assets.
Harbor access, beach access, and neighborhood feel aren't substitutes. They attract different guests, different owners, and different resale buyers.
Destin Harbor and HarborWalk
The harbor district is for buyers who want activity, boating energy, charter culture, restaurants, and event traffic. This is not a pure beach-buyer play. It's a location-driven lifestyle acquisition with a different guest profile and a different rhythm.
Emerald Grande at HarborWalk Village is the clearest example of that positioning. Buyers here are often balancing personal use, walkability, harbor views, and event-oriented rental demand. You trade some of the classic Gulf-front feel for immersion in the commercial and recreational core of Destin.
Central Gulf-front Highway 98 corridor
This is the corridor many buyers picture first. It's the direct beach-access, amenity-driven, high-visibility condo stretch that includes well-known names such as Pelican Beach Resort condos, Sterling Shores, Sterling Sands, Silver Beach Towers, Jade East Towers, and Sundestin Beach Resort.
These buildings don't offer the same investment profile. Some fit pure rental buyers better. Some fit hybrid owners who want heavier personal use. Some command attention because of Gulf frontage, while others rely on amenities, management structure, or pricing relative to the water.
If your priority is Destin condos for sale with the strongest beach-driven identity, this corridor usually deserves first review. If your priority is quieter use, boat access, or a more insulated ownership experience, it may not be the right first stop.
Gulf Front vs Harbor Front A Strategic Analysis
Most buyers default to Gulf-front because it feels safer. That's often the right instinct, but not always for the reasons they think. The strategic choice isn't view versus no view. It's premium revenue potential versus a different demand profile and a different expense stack.
Buyers considering harbor inventory often look closely at offerings like Emerald Grande at HarborWalk Village, because the location logic differs from the beach towers.
Why Gulf-front usually wins on income potential
Gulf-front pricing and rental results vary by building. Ask how Gulf-front units in the building have actually rented before assuming a premium.
That doesn't mean every Gulf-front condo is a great investment. Any Gulf-front advantage depends on the building and the unit checking out.
A clean comparison looks like this:
| Location type | Typical strength | Typical weakness | Best fit |
|---|---|---|---|
| Gulf-front | Direct beach appeal; ask how units in the building have actually rented before assuming a pricing premium | Higher acquisition cost, higher insurance and HOA sensitivity | Buyers prioritizing STR income and long-term prestige |
| Harbor-front | Boating culture, activity, dining access, different guest demand | Less direct beach pull, more variable renter preference | Buyers prioritizing lifestyle mix and harbor access |
Where harbor-front can still make sense
Harbor-front isn't a discount version of Gulf-front. It's a separate category. Guests who choose the harbor usually care about walkability to HarborWalk, boating access, nightlife, fishing charters, and an active social environment.
That can be a smart fit for an owner who plans substantial personal use. It can also fit buyers who think the Gulf-front premium is too expensive relative to their target hold period. But you need to be honest about renter behavior. Guests booking for direct beach time usually start with Gulf-front inventory, not harbor inventory.
Buy harbor-front because you want the harbor experience and accept the tradeoffs. Don't buy it as a substitute for Gulf-front and expect identical rental behavior.
The cost side decides the winner
When assessing Gulf-front properties, investors sometimes get sloppy. Gulf-front can produce better gross revenue, but it also carries more structural cost pressure. Higher insurance premiums and higher HOA obligations can compress net returns if you underwrite loosely. Florida's Office of Insurance Regulation reported an average Okaloosa County condo unit owner premium of $1,754 a year, including wind, as of September 30, 2025. Quotes vary by building and unit.
Harbor-front introduces different costs and demand patterns. It may offer a more flexible acquisition basis in some cases, but it doesn't automatically deliver superior value. It wins only when the net, after all ownership and operating costs, is more attractive for your specific use case.
For pure income buyers, Gulf-front usually stays at the top of the list. For hybrid buyers who want the harbor experience and can tolerate a different revenue profile, harbor-front can be the better personal fit.
The Investor's Underwriting Model for Destin Condos
Buying a Destin condo for income means acting like an operator, not a vacation buyer. If you skip disciplined underwriting, you're not investing. You're speculating with coastal real estate.
A good underwriting model starts with realistic gross revenue, then subtracts every predictable expense line before you judge the asset. That includes costs many buyers gloss over because the listing doesn't make them obvious.
Start with gross revenue, not hope
Rental results vary widely by building, view, season and management, so a market-wide average says little about any one unit. Ask the seller for the unit's own booking history before relying on rental income.
Adjust any comparison for view corridor, Gulf-front position, amenity package, parking convenience, building reputation, and management quality.
Freddie Mac explains how lenders review condo projects.
Build the expense stack correctly
Test the expense side as carefully as the revenue side, so gross revenue does not hide recurring ownership drag.
Your model should include:
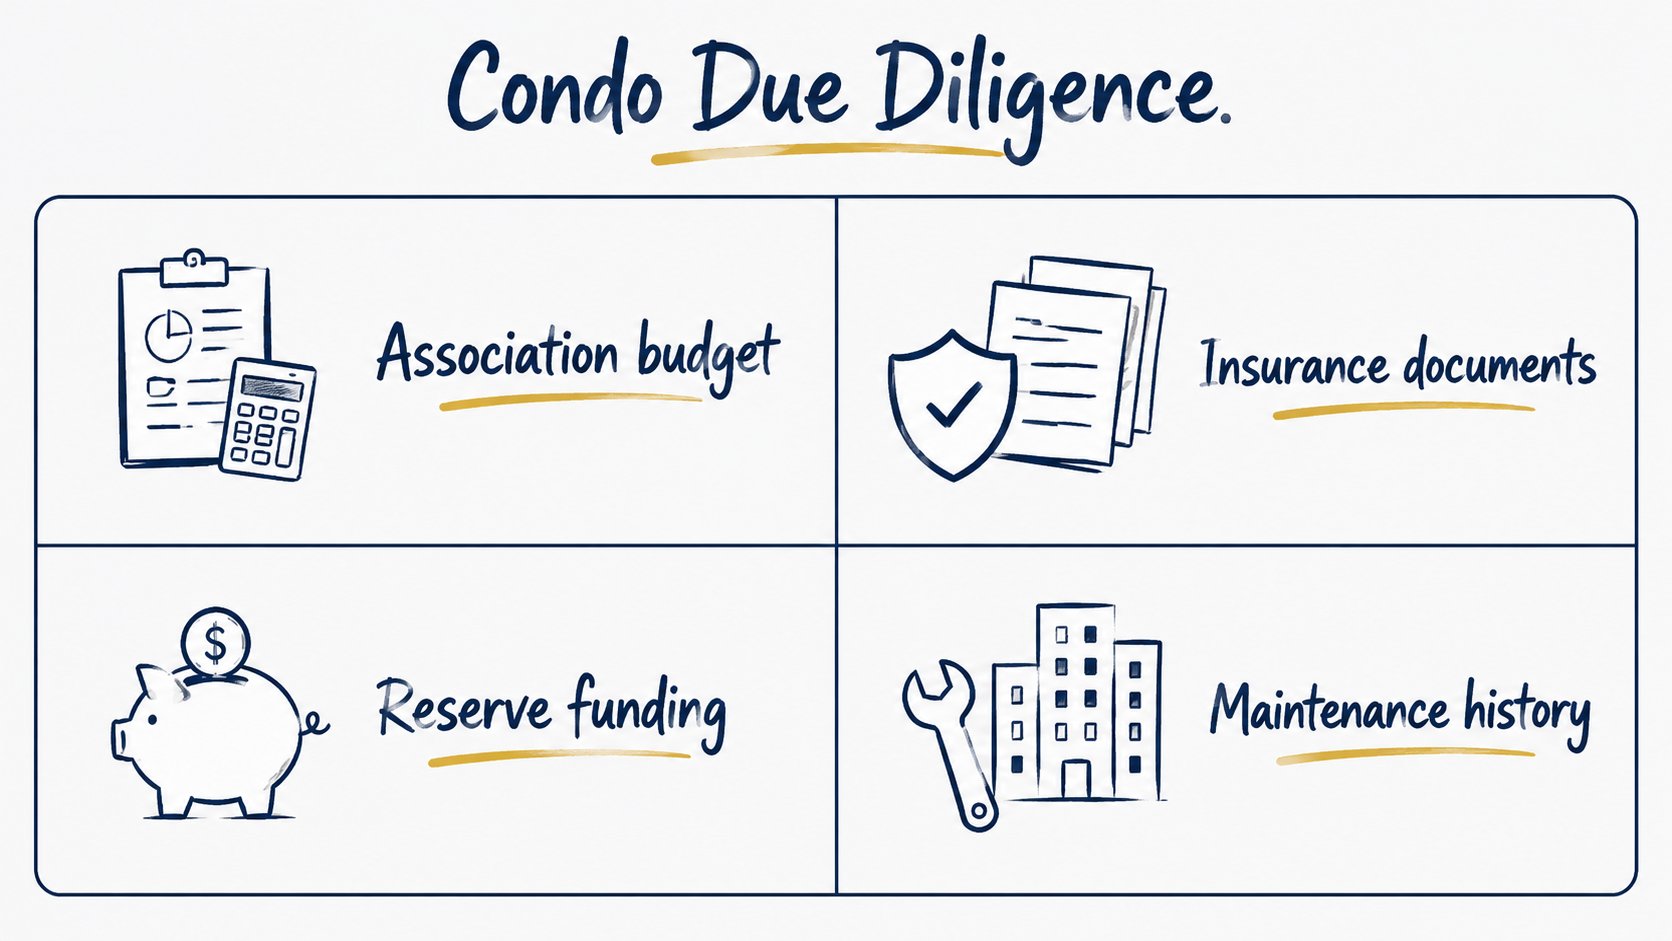
- HOA dues: Review what the association covers and what it doesn't.
- Insurance: Individual policy needs plus the building's broader insurance environment.
- Property taxes: A fixed ownership cost that belongs in every model.
- Management fees: Full-service vacation management can simplify ownership, but it changes your net.
- Cleaning, utilities, and turnover costs: Essential for active short-term rentals.
- Maintenance reserve: Interiors age faster in heavily used vacation units.
- Special assessment risk: This isn't a line item on the listing, but it belongs in your decision.
Underwrite the building, not just the unit
A unit can look excellent and still sit inside a mediocre building. That's why your review needs building-level due diligence:
- Read the condo docs early. Rental policies, pet rules, owner-use restrictions, and pending changes can alter value fast.
- Request financials and budgets. You're buying into a shared operating structure, not just drywall and tile.
- Check management reality. On-site programs can help or hinder flexibility depending on your strategy.
- Evaluate resale depth. Some buildings appeal broadly. Others appeal to a narrow buyer pool.
A beautiful unit in a weak association is still a weak acquisition.
If you want current listing data, HOA direction, and building-level screening, one practical option is to work with Dream Destin Realty's Destin market search platform.
Navigating HOA Rules and Short Term Rental Regulations
Investors love to talk about location and gross revenue. The governing documents usually decide the actual deal.
A condo can look perfect on paper and still fail your strategy because the association limits rental behavior, imposes operational friction, or carries unresolved financial issues. Public listing portals rarely surface that well.
The condo documents matter more than the listing remarks
Your first document review should focus on practical restrictions, not legal trivia. Ask for the declaration, bylaws, budget, current rules, and any recent notices to owners. Then read them with one question in mind: can this building support the way you plan to own and operate the condo?
Focus on these points first:
- Rental minimums: Short-term rental viability can disappear if the minimum stay is too long.
- Use restrictions: Some associations are more owner-oriented than investor-oriented.
- Pet policies: That matters for second-home owners and for a slice of the rental market.
- Pending assessments or litigation: These issues can affect financing and future cash calls.
- Operational limits: Parking, amenity restrictions, and guest check-in rules can influence reviews and repeat bookings.
A buyer evaluating active inventory such as The Palms of Destin on Indian Bayou Trail should treat the building package as seriously as the unit tour.
Licensing and compliance can change the whole deal
Generic search sites have a blind spot here. Portal listings rarely show how insurance costs affect underwriting on older Gulf-front buildings. That cost pressure alone can alter your net yield assumptions.
The same broad theme shows up in short-term rental compliance. Florida's short-term rental licensing framework has grown more detailed in recent years, and listings don't always spell out what a specific building requires, from active business tax receipts to local registration steps. If compliance details aren't clear, the underwriting isn't finished.
If a listing can't answer how the building handles rentals, registration, and operating rules, you don't have enough information to price the asset.
The right move is simple. Don't rely on listing remarks. Get the documents. Read the rules. Confirm the association's current operating posture before you commit earnest money.
Advanced Investment and Financing Considerations
Discerning buyers don't stop at "Will this rent?" They ask how the property fits the broader portfolio, how financing structure affects returns, and whether this is the right replacement asset for tax planning.
1031 strategy and income durability
For exchange buyers, Destin condos can work extremely well when the acquisition is driven by income durability and resale appeal.
Exchange buyers should avoid broad market averages and focus on irreplaceable location and building quality. Replacement property selection should emphasize durability, not just immediate excitement.
Financing and management choices change returns
The debt side matters more in condos than many buyers expect. Some resort-style properties can trigger more lender scrutiny because the building profile doesn't fit a plain-vanilla conventional template. A loan that looks attractive at first can become less attractive once reserve requirements, project review, and insurance questions surface.
Property management structure matters just as much. Your options usually fall into three camps:
- Full-service local manager: Lower operational burden, but you need to understand fee drag and owner-use limitations.
- Lean third-party coordination: More flexibility, more oversight required from you.
- Hands-on ownership model: Highest control, but only practical if you can actively manage vendors, guests, and compliance.
A buyer comparing alternatives like Gulf Terrace condos in Destin should judge financing and management together. A property with lower friction on both fronts can outperform a prettier unit with operational headaches.
The right condo isn't the one with the strongest gross projection. It's the one whose financing, management model, and ownership costs still make sense after the excitement wears off.
For second-home buyers, this section matters too. A condo that's easy to finance, easy to insure, and easy to manage will usually be held longer and sold more confidently.
Your Acquisition Framework for a Destin Condo
Good acquisitions follow a sequence. Bad ones start with a favorite building and then force the numbers to fit. Reverse that process.
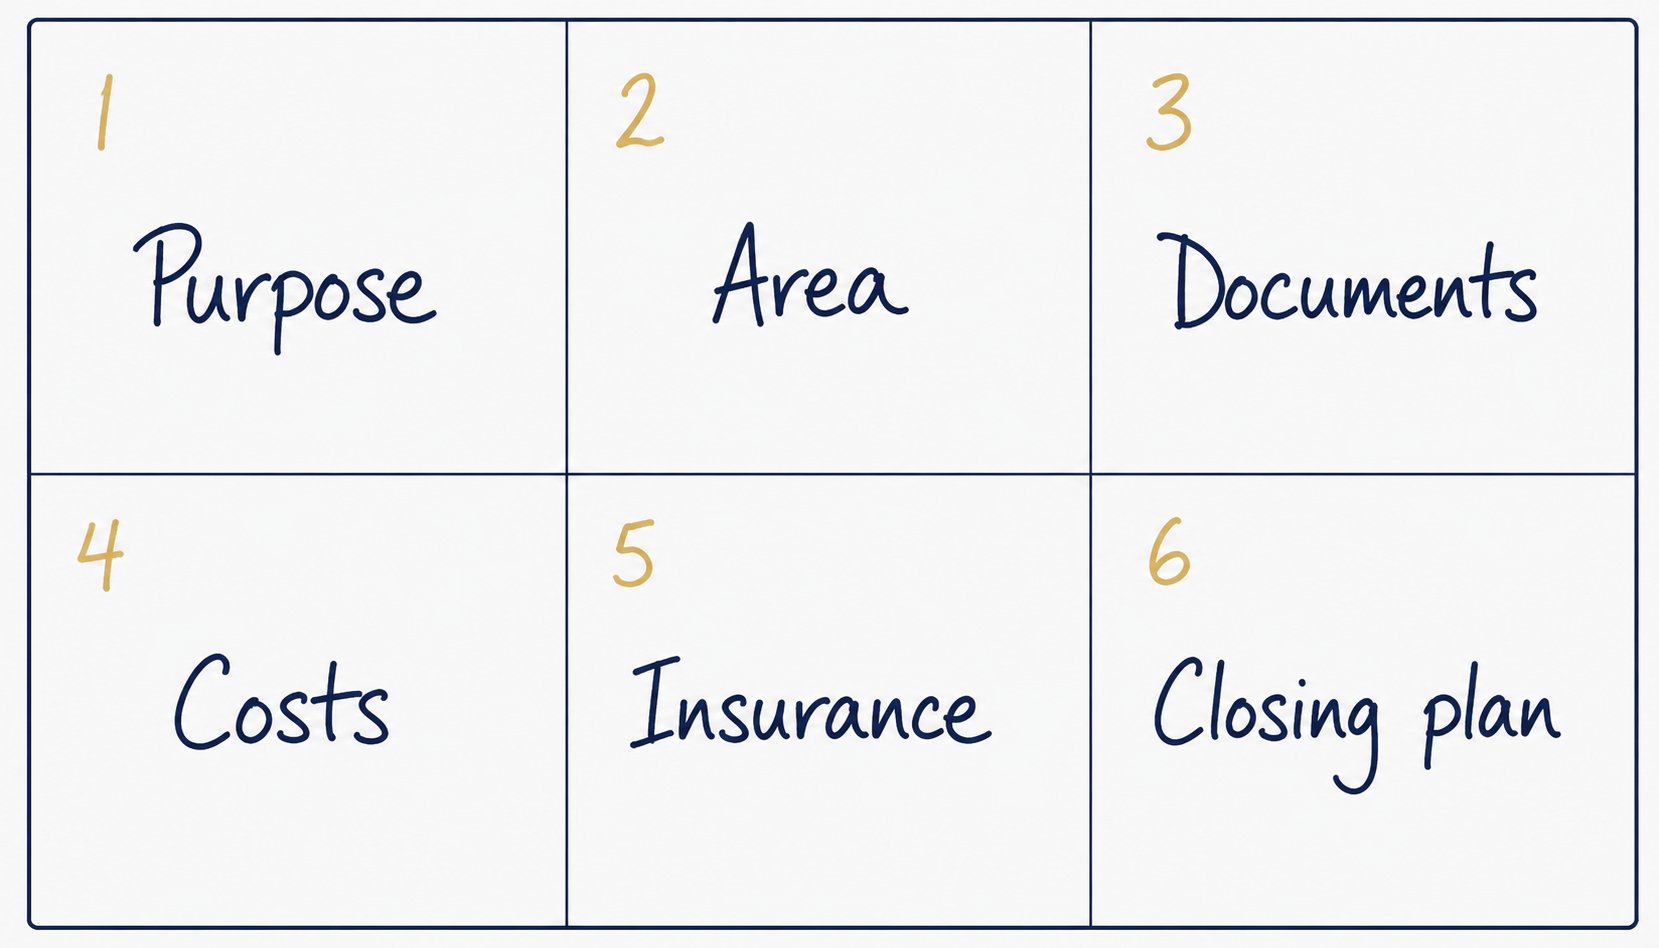
A disciplined six-step approach
- Define the mandate. Decide if you're buying for pure STR income, a hybrid second-home strategy, or long-hold wealth preservation.
- Choose the submarket. Holiday Isle, Crystal Beach, the harbor district, and the central Gulf-front corridor serve different ownership goals.
- Narrow to buildings. In Destin, building selection is often more important than unit finishes.
- Underwrite thoroughly. Start from the unit's own documented booking history, then stress-test expenses, restrictions, and downside scenarios.
- Negotiate like a buyer, not a tourist. Push on pricing and terms once the documents check out.
- Set up operations before closing. Insurance, management, compliance, and post-close vendor planning should be lined up in advance.
Where execution usually breaks down
Most buyers fail in one of three places:
- They chase a view instead of a business case.
- They underestimate HOA and insurance drag.
- They wait too long to review association documents.
That last one is the most expensive. By the time a bad rule set shows up late in escrow, your position is less favorable and your time is wasted.
If you're serious about buying one of the better-positioned Destin condos for sale, act like you're acquiring a small operating business with a beach component. That's the right frame. It protects your capital and usually leads you to a better property.
If you're weighing Gulf-front, harbor-front, or lifestyle-driven condo options in Destin, contact Dream Destin Realty for current listings and help gathering association and building records.


