
Destiny by the Sea Homes for Sale: A 2026 Buyer Guide
Explore destiny by the sea homes for sale in Destin, FL, including pricing context, HOA rules, insurance factors, and what to verify before you buy.

Destiny by the Sea homes for sale sit in a luxury micro-market, with a 2026 median sale price ranging from $1.66 million to $1.85 million and roughly 11 active homes. That isn't broad Destin housing. It's a limited coastal enclave where inventory, property condition, association obligations, and insurance can matter as much as the asking price.
The comparison is stark. Destin's broader 2026 median sale price was reported around $556,197 to $566,667, while Destiny by the Sea commands a materially higher position within the city. Buyers searching this community should evaluate each property against recent closed sales, not against a generic Destin search result or a seller's rental narrative.
Table of Contents
- What Destiny by the Sea Looks Like as a 2026 Market
- Inside the Gated Community Boundaries and Housing Stock
- HOA Dues, Deed Restrictions, and What Buyers Should Expect
- Insurance Realities for Coastal Luxury Owners
- Reading the Active Listings Like a Buyer
- Short-Term Rental Assumptions to Verify Before You Buy
- Financing, 1031 Exchange Timelines, and Investor Basics
- Your Offer-to-Closing Checklist and Next Steps
What Destiny by the Sea Looks Like as a 2026 Market
The current numbers point to a market with scarcity and slow price discovery. A 2026 neighborhood snapshot placed Destiny by the Sea's median sale price at $1.85 million, based on 106 tracked homes, with a median 238 days on market. A separate view for Destiny by the Sea S/D reported a $1.66 million median sale price and 108 median days on market. Those figures aren't interchangeable, but they tell the same story. Homes can remain available for months, and a small set of transactions can move the median materially. The local Destiny and Destin market snapshot provides both submarket and citywide context.
Broader Destin moved faster than the neighborhood snapshot, although it wasn't a quick market. Redfin reported a $556,000 median sale price, a 1.7% year-over-year increase, and a median 98 days to sell for the three months ending June 2026. Zillow reported 73 days to pending, a 0.950 median sale-to-list ratio, 4.1% of sales closing over list, and 787 active listings. Redfin's Destin housing market data and Zillow's Destin market snapshot show why a Destiny by the Sea listing shouldn't be priced by applying a citywide average.
Destiny by the Sea versus broader Destin in 2026
| Metric | Destiny by the Sea | Greater Destin |
|---|---|---|
| Median sale price | $1.66 million to $1.85 million | About $556,000 to $566,667 |
| Median time on market or related timing | 108 to 238 days on market | 98 days to sell, 73 days to pending |
| Inventory | About 11 active homes | 787 active listings in Zillow's snapshot |
| Market character | Tight luxury enclave | Broader, more varied city market |
I don't treat the 11 active homes as a measure of healthy liquidity. In a community this small, one gulf-front listing and one interior residence may have almost nothing in common besides the neighborhood name. That makes price-per-square-foot comparisons, lot position, frontage, construction quality, elevator systems, roof age, and documented rental rights more useful than a simple median.
For broader neighborhood context, buyers can also compare Destin condominium insights, but condos and single-family homes carry different association, insurance, and maintenance questions.
Inside the Gated Community Boundaries and Housing Stock
Destiny by the Sea functions as a near-micro-market within Destin. Its value depends on a small supply of coastal parcels, precise location, recorded rights, and the condition of each home. Public market materials associate the gated community with Ocean Boulevard and Destin's Gulf-front area, but the property-specific title, plat, declaration, easements, and resale package control the legal boundaries and ownership obligations.
Nearby communities with similar names can follow different rules. Gates, amenities, fees, leasing provisions, parking standards, maintenance duties, and access rights require separate verification. A buyer should identify the exact phase, lot or unit, common elements, and association structure before comparing a listing with another property.
Match the home type to the use you actually want
The housing stock generally includes large detached coastal residences, including gulf-front, second-row, and interior positions, as well as some attached villa-style homes. Each category carries a different ownership profile:
- Gulf-front homes may justify a location premium, but direct exposure increases the importance of reviewing the building envelope, glazing, roof, corrosion, wind, and flood conditions.
- Second-row properties can provide beach proximity without direct frontage. Confirm view corridors, pedestrian routes, and access rights in the recorded documents instead of relying on listing language.
- Interior homes may offer more privacy, different lot configurations, and another price point. Verify views, parking, walk routes, and common-area access for the specific parcel.
- Attached villas require close review of the declaration, maintenance boundaries, shared insurance, and association responsibilities.
MLS descriptions can identify bedrooms, views, pools, elevators, or beach access. They do not establish the legal boundaries or rights conveyed with the deed. Require a survey, title commitment, recorded easements, current community documents, and confirmation of the road and gate arrangement.
Practical rule: Treat “walk to the beach,” “private access,” and “Gulf view” as claims to verify against the survey, title commitment, recorded easements, and current community documents.
Scarcity changes how you should read the resale market. A gulf-front estate, second-row home, and interior residence may appear together in one search while attracting different buyers, lenders, and insurance costs. Build the comparison set by frontage, position, finished area, lot, age, renovation history, insurance profile, documented use, and days on market. Headline list price and community name are weak guides without that property-level work.
For broader neighborhood context, use the Destin homes for sale and neighborhood investment guide, then narrow the analysis to the recorded parcel and its total cost of ownership.
HOA Dues, Deed Restrictions, and What Buyers Should Expect
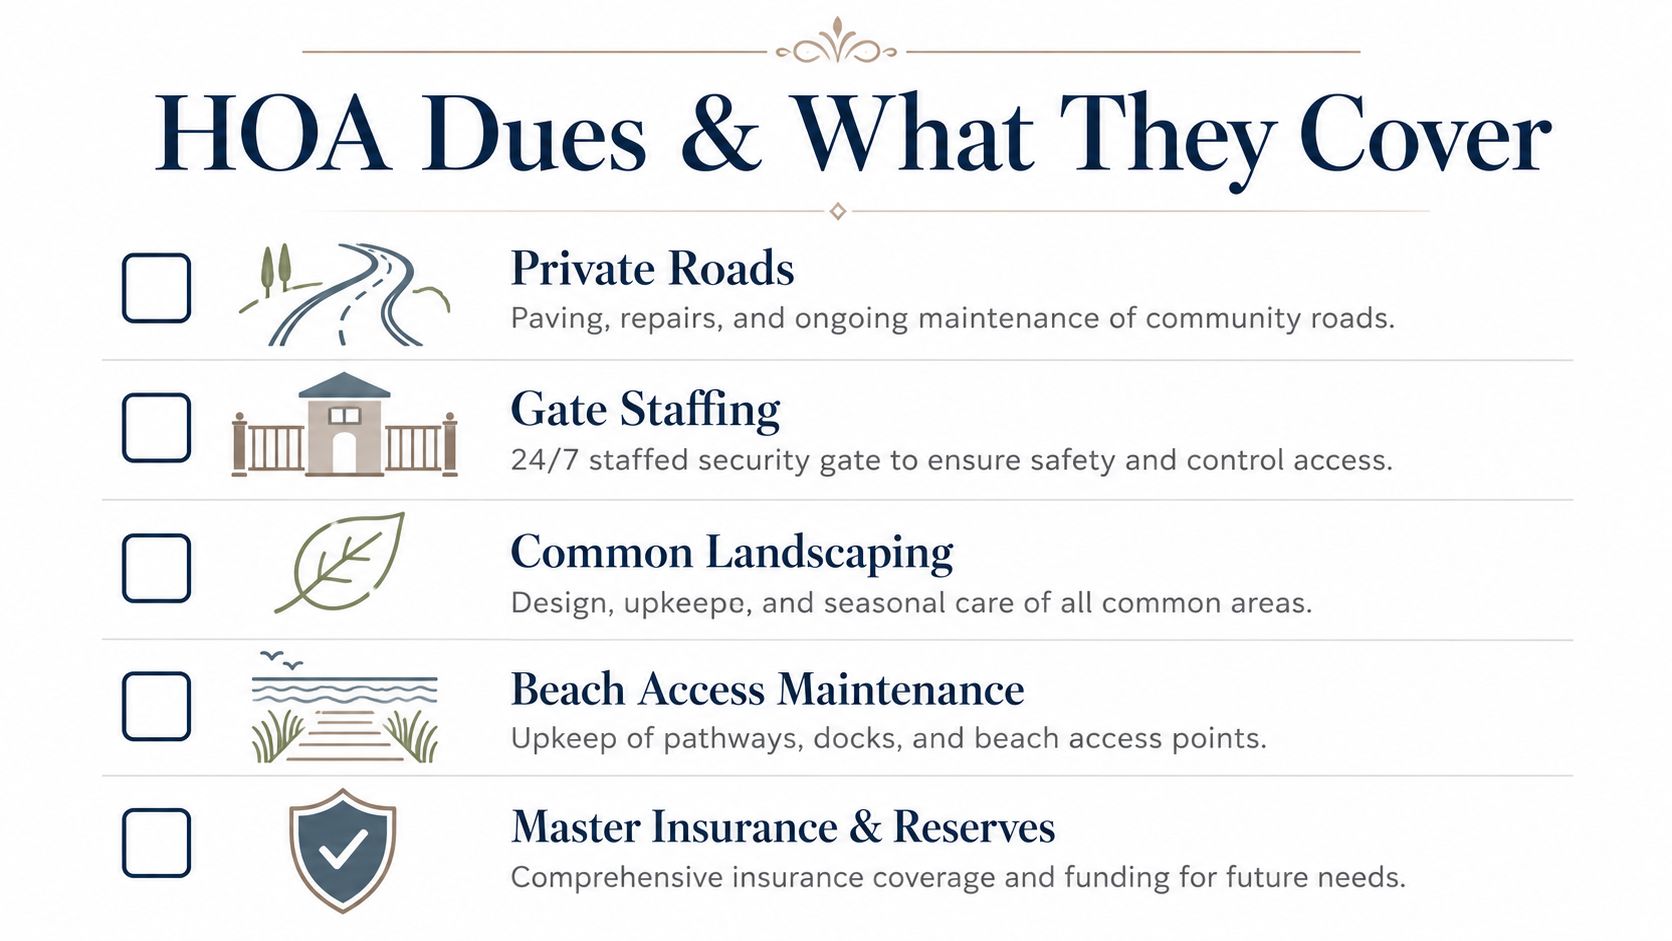
Published property information lists quarterly HOA dues around $1,463, or about $488 per month, for some Destiny by the Sea properties. Reported services include accounting, grounds maintenance, management, security, and recreational facility upkeep. Use the published property and HOA information as a starting point, not as proof of the current obligation for a specific home. Request the latest estoppel, budget, declaration, amendments, and written association confirmation before pricing the purchase.
This fee reflects more than routine landscaping. Security, common-area preservation, management, and recreational upkeep affect carrying costs, resale comparisons, lender review, and exposure to future assessments. Confirm whether the quoted dues apply to the exact lot or villa, whether the account is current, and whether a master or sub-association charges anything separately.
Build the ownership file before relying on the dues
Obtain these records during due diligence:
- Current budget: Check operating expenses, reserves, insurance, management, and maintenance responsibilities.
- Resale certificate or estoppel: Verify unpaid assessments, transfer charges, violations, and account status.
- Declarations and amendments: Confirm leasing rules, architectural controls, parking, pets, occupancy, and use restrictions.
- Insurance certificates: Identify association coverage and the costs left to the owner.
- Assessment notices: Determine whether an approved or proposed assessment affects the property.
Treat rental history as evidence of past use only. Current permission depends on the governing documents, and association rules may exceed city zoning. Exterior work, fences, pools, landscaping, paint, storm protection, and mechanical equipment may require architectural approval.
Buyers and sellers handling association records can consult this guide to selling HOA properties in Florida. For a Destiny by the Sea purchase, the recorded declaration and current association documents control.
Insurance Realities for Coastal Luxury Owners
Insurance can break a coastal luxury transaction after the buyer has already negotiated the price. Flood, wind, homeowners coverage, deductibles, replacement cost, roof condition, elevation, construction details, and lender requirements all affect the true ownership budget. None should be estimated from the neighborhood name alone.
The City of Destin participates in the National Flood Insurance Program. Flood insurance is mandatory when a property sits in a Special Flood Hazard Area and the loan is secured by a federally backed mortgage. Destin's CRS Class 6 rating can provide up to a 20% discount on standard flood insurance policies, but the city makes clear that the practical result depends on the property and policy. Destin's flood insurance guidance should be read alongside the parcel's FEMA information and the lender's requirements.
Build the insurance file around the address
Don't assume two homes on the same street have identical premiums. Confirm the exact flood zone, elevation information, foundation, lowest floor, utilities, roof age, wind mitigation features, prior claims, replacement-cost valuation, and the availability of wind and flood coverage.
| Coverage line | Buyer action item |
|---|---|
| Flood | Obtain the current flood-zone information and ask whether an elevation certificate is available. |
| Wind | Confirm whether wind is included, separately written, or subject to a distinct deductible. |
| Homeowners | Request a replacement-cost estimate and identify exclusions affecting coastal construction. |
| Roof and systems | Verify roof age, remaining useful life, permits, and inspection requirements. |
| Lender conditions | Give the binder and inspection reports to the lender early, not after the inspection period. |
A four-point inspection and wind mitigation inspection may affect underwriting, but the required reports and acceptable age vary by carrier and lender. Ask for prior inspection reports, permits, repair invoices, and seller disclosures, then obtain fresh reports when required.
Insurance should be quoted before you write the offer, not after the inspection deadline.
The City of Destin CRS credit is a potential policy benefit, not a universal promise of a particular premium. Have the insurance agent confirm eligibility against the exact address, policy form, mortgage structure, and flood zone.
Reading the Active Listings Like a Buyer
An active listing signals interest, not confirmed value, especially in a community this small. With roughly 11 homes for sale, a neighborhood median list price of $1,999,950, and a median 175 days on market, the current pool offers limited direct comparison. Realtor.com's Destiny by the Sea market page supports that inventory and list-price snapshot.
Days on market deserve more attention than the headline asking price. Longer exposure can reflect luxury financing, insurance review, unusual floor plans, limited comparable sales, or a seller willing to wait. Treat the listing as a starting file, then test the price against the property's position, condition, documents, and recent comparable sales.
What to inspect in the listing history
Read the complete sequence before judging the current ask:
- Original list price: Compare it with the current price and record every change date.
- Cumulative market time: A relist can reset the public clock even when the home has been marketed much longer.
- Status changes: Active, pending, withdrawn, and coming-soon entries carry different implications.
- Property position: Gulf frontage, second-row placement, interior location, access, lot, and views can change value sharply.
- Physical condition: Require support for the roof, windows, HVAC, elevators, pools, decks, exterior finishes, and storm repairs.
The wider market's reported 0.950 sale-to-list ratio indicates that negotiation occurs beyond this neighborhood, but it cannot set the right discount for one Destiny by the Sea home. A well-maintained property with verified records may command firmer terms than a listing with stale inspections, unresolved association questions, or incomplete repair documentation.
Use Dream Destin Realty property listings to monitor available homes, then request a parcel-level comparison separating gulf-front, second-row, interior, and attached inventory. Review the full listing history, HOA documents, inspection records, and seller disclosures before relying on any suggested value. A rental projection, prior advertisement, or marketing statement is only an assumption until its supporting records are verified.
Short-Term Rental Assumptions to Verify Before You Buy
A beachfront address does not establish short-term rental rights. Destiny by the Sea functions like a near-micro-market, where HOA controls, parcel-specific zoning, insurance terms, and operating costs can matter more than the headline list price. Get written confirmation for the exact property and rental period before counting projected income in your offer.
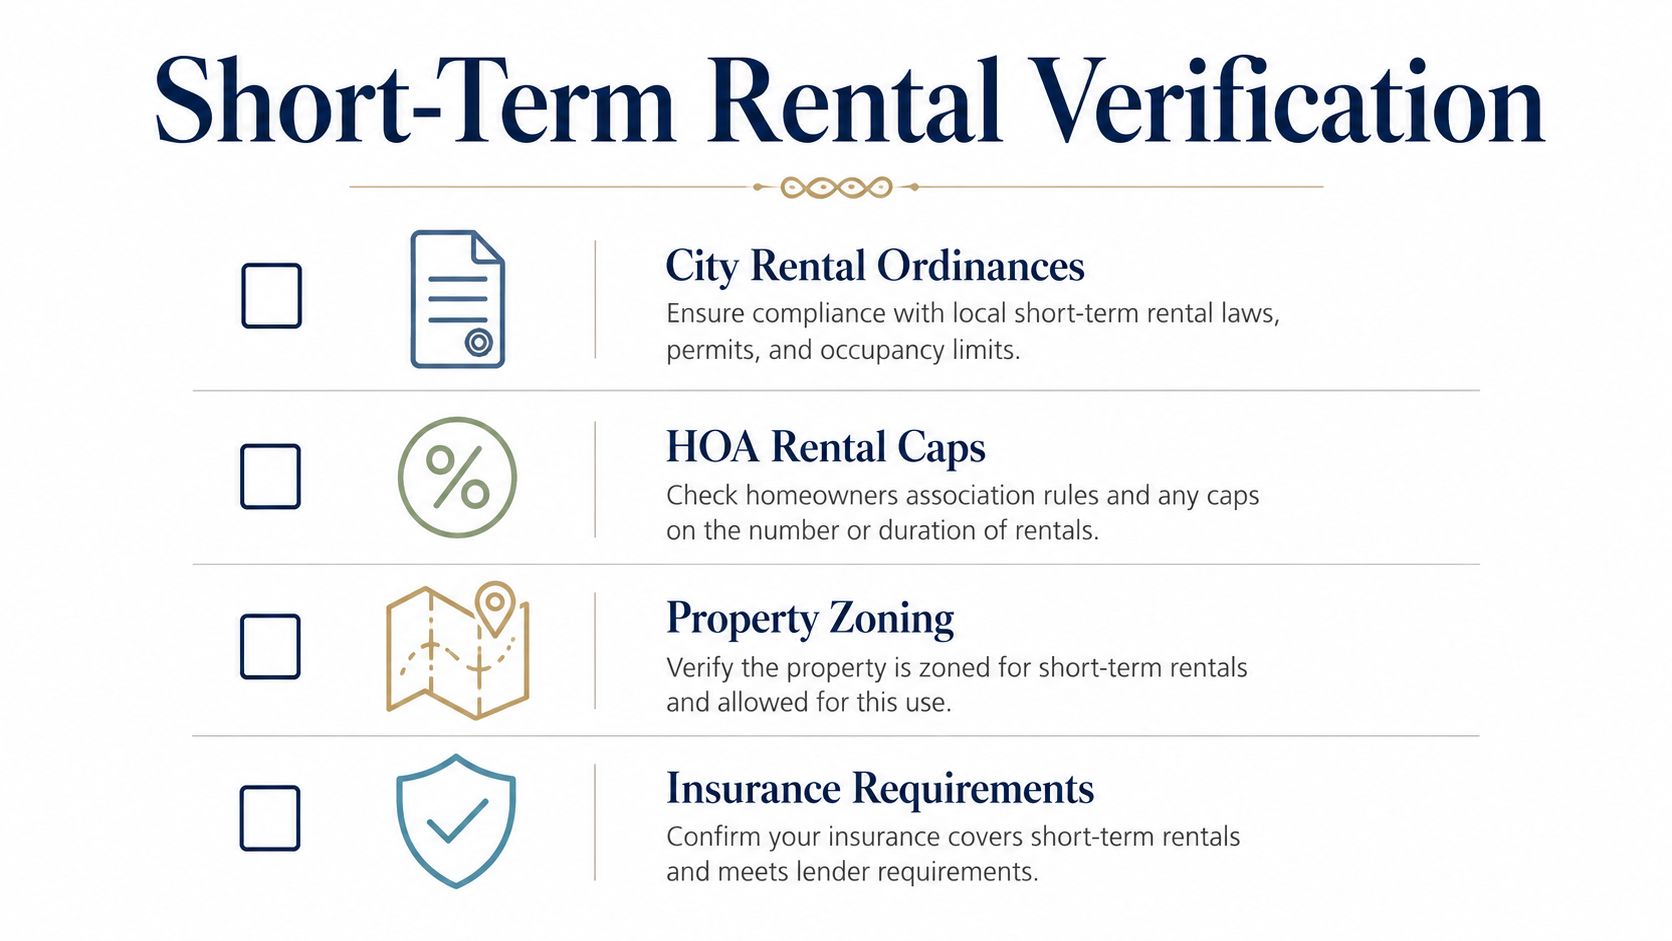
Destin permits short-term rentals only in specified zoning districts, including Bay Resort Mixed Use, Crystal Beach Resort, Calhoun Mixed Use, Crystal Beach Neighborhood, Holiday Isle Mixed Use, North Harbor Mixed Use, South Harbor Mixed Use, and ROI-TD. The city limits overnight occupancy to two adults per bedroom plus four additional persons, with a maximum of 24 persons per house. Destin's short-term-rental FAQ identifies these municipal requirements.
Build the permission file before underwriting income
Request these records before treating a rental projection as part of value:
- Zoning confirmation: Match the written answer to the parcel identification and current zoning.
- Association documents: Read the declaration, amendments, leasing rules, minimum terms, rental caps, and enforcement history.
- Registration records: Confirm required city registration and its current status.
- Tax accounts: Verify applicable state and local registrations and remittance duties.
- Insurance approval: Ask the carrier whether the intended rental use is covered and under what conditions.
- Operating records: Review seller-provided rental statements as historical evidence, not permission or a forecast.
The HOA may impose tighter limits than the city. That distinction affects both income and resale risk, so do not rely on an agent's summary or a prior listing. Require the governing documents and written confirmation.
Properties outside Destin, including those in South Walton or the 30A area, follow different county requirements. Walton County requires annual short-term vacation-rental registration, with fees of $300 per property for an individual registration and $227 per property for a community registration, effective February 1, 2025. Registrations renew by May 31 each year, and county guidance states that state and tourism tax registrations come first. Walton County's vacation-rental registration information applies to that jurisdiction, not automatically to Destiny by the Sea.
Use the 2026 playbook for hosts for operating questions only after legal permission is documented. It does not replace zoning confirmation, registration, insurance approval, or association consent.
Once permission and expenses are verified, discuss how to maximize ROI with Dream Destin Realty. Start with actual costs, HOA controls, insurance, maintenance, and vacancy assumptions. Rental income is an underwriting input, not a guarantee.
Financing, 1031 Exchange Timelines, and Investor Basics
A Destiny by the Sea purchase can fail on financing even when the buyer qualifies on income. Coastal luxury collateral requires the lender to assess comparable sales, property condition, insurance availability, flood exposure, association obligations, and intended use. Ask for a property-specific preapproval strategy before submitting an offer. Limited comparable sales or unusual improvements can change the appraisal and loan structure.
Send the lender a complete file early: contract, income and asset records, insurance materials, inspection reports, title information, association documents, budget, and estoppel. The lender may also require proof that the property can legally be used as described. A previous rental listing does not establish that permission.
The federal exchange clock is unforgiving
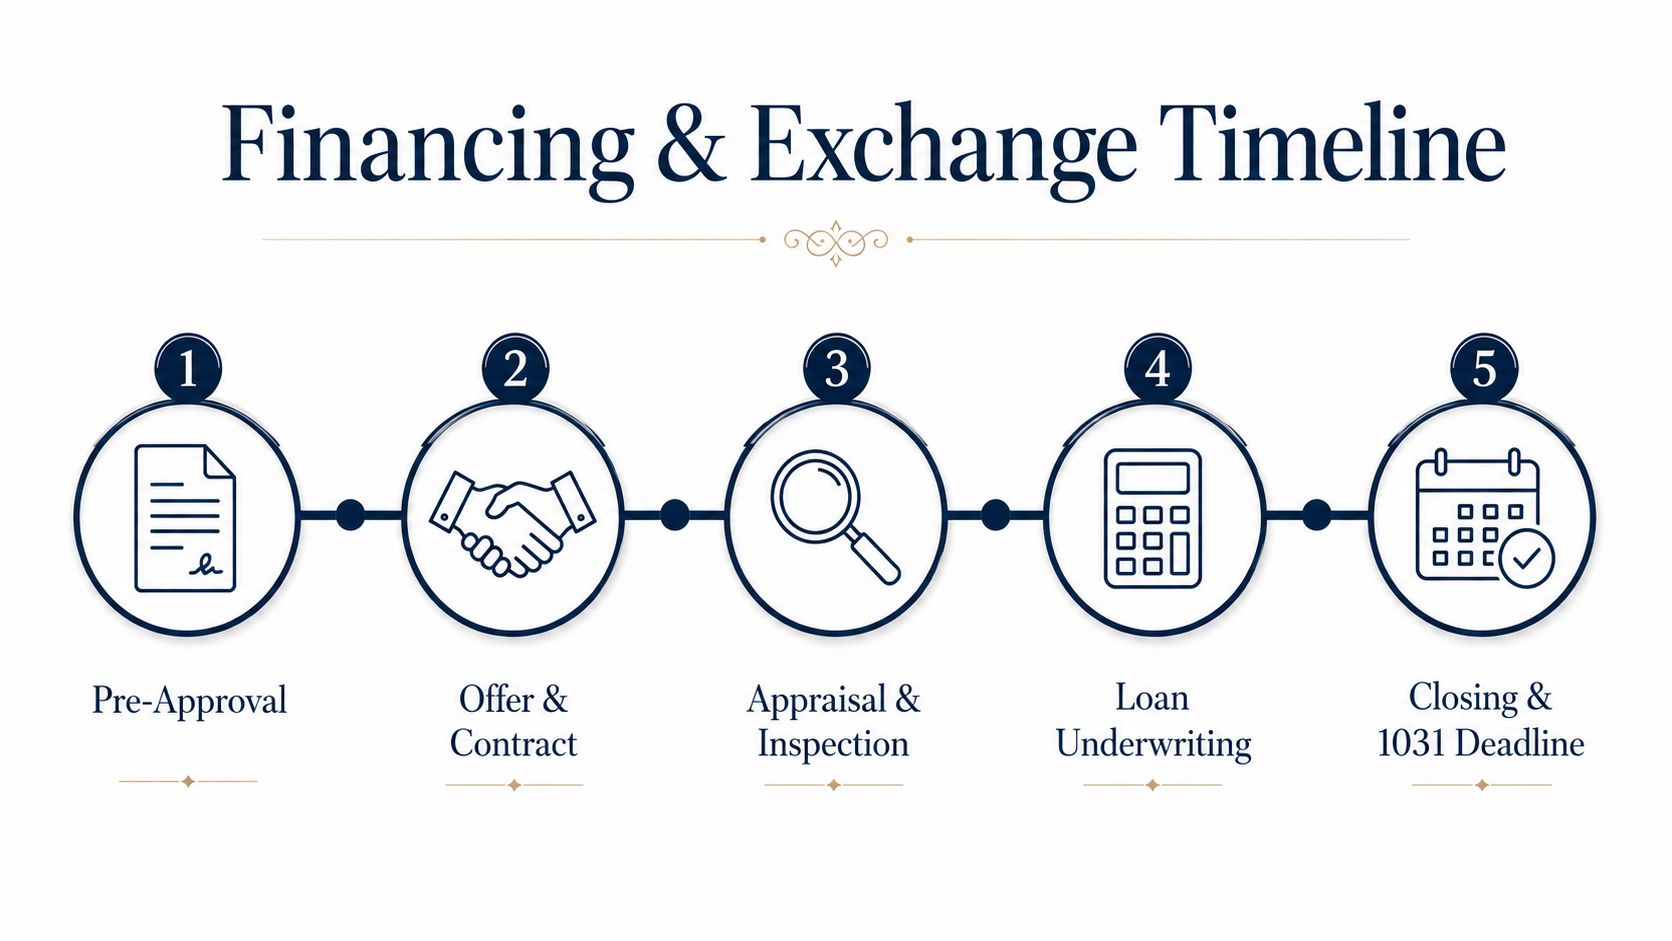
A 1031 exchange defers tax only when real property held for investment or productive use is exchanged for like-kind real property held for the same purpose. The replacement property must be identified in writing within 45 calendar days after closing the relinquished property. The exchange must close within 180 calendar days, or by the tax return due date including extensions, whichever comes first. The federal 1031 exchange explanation summarizes these requirements.
Personal use can disqualify an otherwise attractive second-home strategy. Have your CPA and qualified intermediary review how both properties were held, how personal occupancy is treated, and which records support the exchange. A real estate attorney should examine title, deed restrictions, association documents, and contract terms before deadlines become difficult to fix.
Coordinate the transaction by decision point:
- Before the offer: Confirm the exchange structure, borrowing capacity, and document deadlines.
- After contract: Send the contract and property file to the lender, CPA, intermediary, and attorney.
- During diligence: Resolve title, inspection, insurance, association, and permitted-use questions.
- Before closing: Confirm funds, identification paperwork, final underwriting, and title clearance.
Review the 2026 1031 exchange rules and timelines before choosing a replacement property. Treat the exchange calendar as a closing constraint, not an administrative detail. A delayed inspection, unresolved insurance issue, or incomplete association file can leave the buyer with fewer workable choices. In this near-micro-market, total ownership costs and document quality matter more than headline list price.
Your Offer-to-Closing Checklist and Next Steps
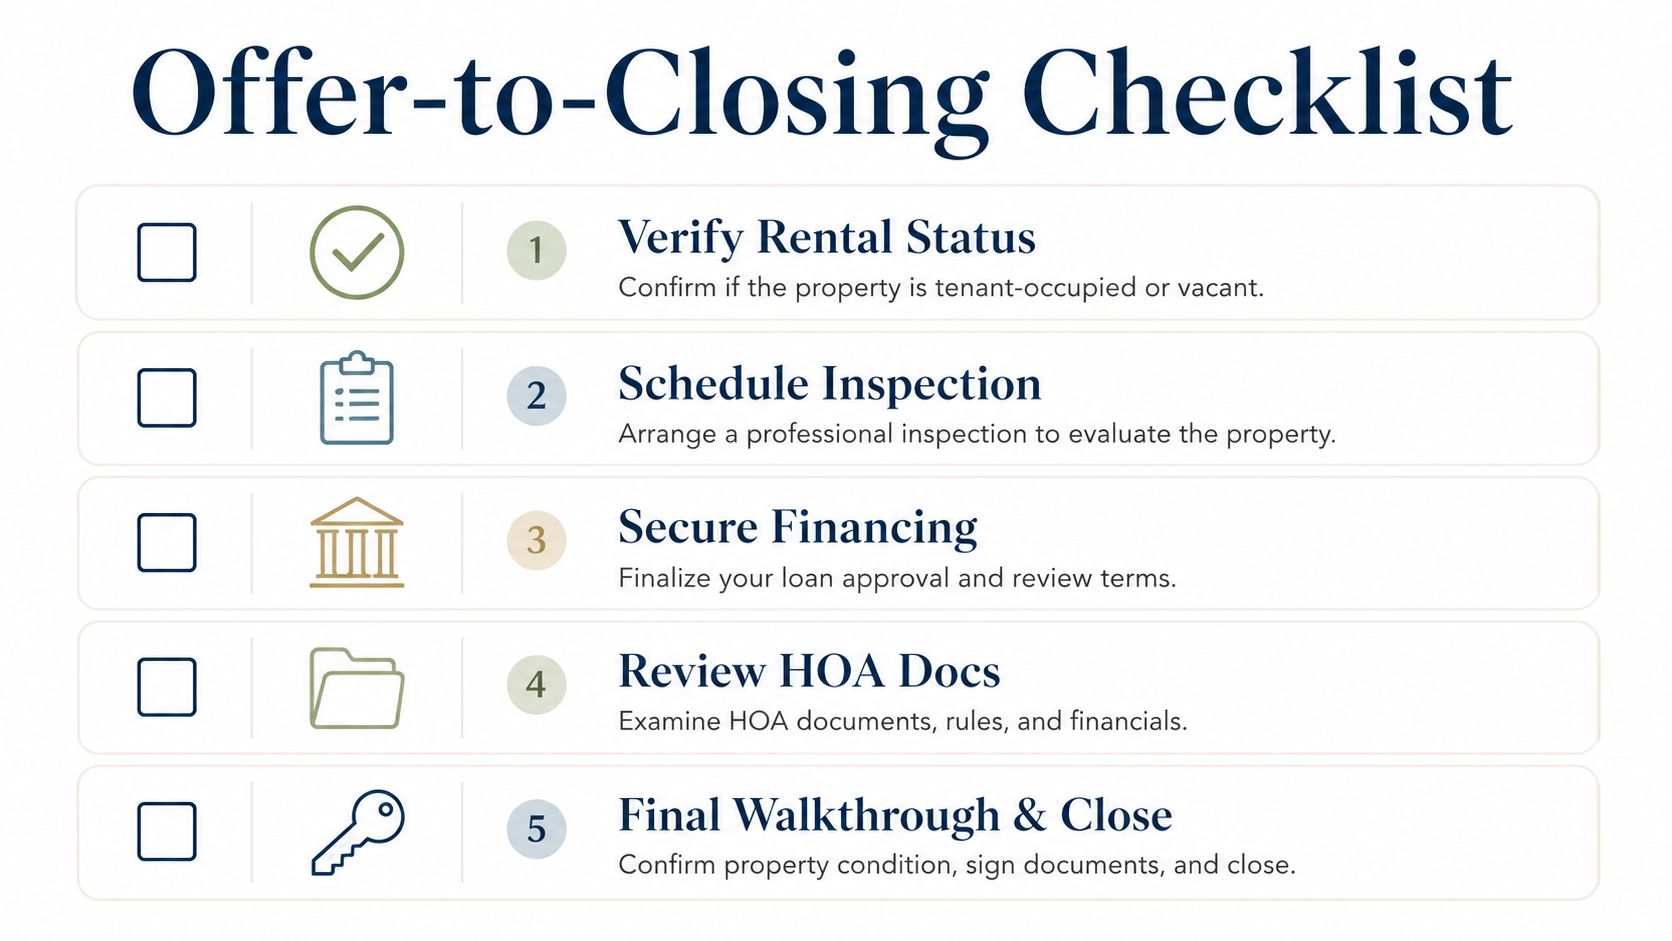
Start with the parcel, not the brochure. Once a Destiny by the Sea home goes under contract, assign each verification to the professional who can answer it and set deadlines inside the inspection period.
- Confirm intended use in writing. Ask the City of Destin about the parcel's zoning, registration status, occupancy limit, and current requirements. Obtain the association's written leasing position for the exact home and desired rental term.
- Order coastal inspections. Schedule the general inspection, wind mitigation review, roof evaluation, and flood-related review. Request an elevation certificate when available and confirm whether the lender or carrier needs additional documentation.
- Secure insurance early. Obtain flood, wind, and homeowners quotes, then request a binder acceptable to the lender. Review deductibles, exclusions, replacement-cost assumptions, and prior claims.
- Pull association records. Order the estoppel, current budget, declarations, amendments, meeting materials, insurance certificates, assessment information, violation history, and architectural approvals.
- Clear title and financing. Review the title commitment, survey, easements, legal description, permits, appraisal, and underwriting conditions before the closing date.
- Recheck the property before funding. Confirm agreed repairs, personal property, operating systems, storm damage, access devices, and the condition shown in the contract.
Roof age and inspection gaps can stop a coastal closing when the insurer or lender won't accept the risk. HOA leasing caps, unapproved improvements, unpaid assessments, flood-zone complications, and missing permits create similar problems. Deal with those issues before the buyer's contingency rights expire.
Set your search to the Destiny by the Sea community and monitor the current luxury price band instead of assuming every active listing is comparable. Ask for closed and withdrawn comparables, cumulative days on market, parcel-level insurance information, association documents, and an off-market review before your next showing. A clear process for how to find a Destin agent can help you evaluate representation around those specific tasks.
Visit the Destiny by the Sea homes for sale page to see current availability and request a community-specific offer-to-closing review.
Dream Destin Realty can help you compare active and off-market Destiny by the Sea opportunities, organize parcel-level comps, and coordinate association, insurance, inspection, financing, and title questions before you commit. Visit Dream Destin Realty to request a focused buyer consultation for your next Destiny by the Sea purchase.


