
Buying a House Sight Unseen: A Remote Purchase Guide
Before buying a house sight unseen, check flood risk, insurance, inspections, records and contract deadlines on the Emerald Coast.

On this page
On this page
Buying a house sight unseen means committing to a property you have not toured in person, relying instead on a representative, an independent inspector, public records and written contract terms. It can work, but only when independent evidence confirms flood exposure, insurance feasibility, physical condition and records before the buyer's contract rights expire.
Table of Contents
- What Buying a House Sight Unseen Involves
- Screen Flood and Insurance Before You Offer
- Run a Live Video Walkthrough That Tests Details
- Order Inspections, Appraisal and Wind Mitigation
- Review Records and Track Contract Deadlines
- Handle Local Logistics From Out of Area
- Decide Whether the Remote Purchase Passes Your Checks
What Buying a House Sight Unseen Involves
A remote purchase replaces the buyer's personal walkthrough with a designated representative, an independent inspector, public records and written contract terms. It shouldn't replace verification with confidence in photographs.
The process has distinct stages:
- Pre-offer screening: Establish whether the address, likely ownership costs and available records justify pursuing the property.
- Property verification under contract: Investigate condition, obtain specialist findings and resolve document questions within the negotiated review periods.
- Final checks before closing: Confirm agreed repairs, included items, access arrangements and the property's current condition.
A virtual tour helps with orientation and narrowing candidates. It doesn't reliably establish odors, noise, moisture, slope or concealed defects. Emerald Coast purchases also warrant deliberate attention to flood, wind and association obligations.
The guide to buying a house with Dream Destin Realty provides broader purchase context. For a remote purchase, the immediate decision is narrower: pause before offering if an address-specific flood map or property-specific insurance quote can't be obtained.
Screen Flood and Insurance Before You Offer
| Check | Where to verify | What it settles | Stop signal |
|---|---|---|---|
| Flood zone | FEMA Flood Map Service Center, address-specific map extract | Mapped flood designation; lender confirms the loan's insurance requirement | Property can't be located or its map designation is unclear |
| Flood insurance quote | Licensed agents quoting the exact address | Proposed coverage availability and cost, subject to underwriting | No quote available for the address |
| Association or condominium documents | Records requested through the buyer's representative | Budget, reserves, assessments, litigation and rental rules | Reserve or litigation information is missing or unclear |
| Seller flood disclosure (residential sales) | Disclosure required by section 689.302, Florida Statutes, at or before contract signing | Whether the seller knows of flood damage during the seller's ownership, filed a flood-damage insurance claim or received flood-damage assistance, such as from FEMA | Disclosure unavailable before signing |
The first checks belong before an offer; the disclosure belongs at the signing gate. These are recommended decision thresholds, not universal statutory pre-offer requirements.
Enter the address in FEMA's Flood Map Service Center guidance, open the dynamic map and examine the applicable map extract. The Florida Office of Insurance Regulation's flood-insurance guidance says homeowners in high-risk areas with mortgages from federally regulated or insured lenders must carry flood insurance, and that coverage is recommended, though not required, in moderate to low-risk areas. Distance from the shoreline doesn't settle either question.
Request property-specific flood and wind coverage quotes from licensed insurance agents. Compare ordinary and storm-related deductibles, exclusions and outstanding underwriting conditions. A quote isn't a coverage binder or a promise of future premiums.
For association property, planning your Emerald Coast condo purchase should include requesting building records early, rather than treating the unit's appearance as evidence of the association's finances.
Run a Live Video Walkthrough That Tests Details
The buyer's representative should direct the walkthrough independently of the seller's marketing. A polished presentation isn't the same as an examination.
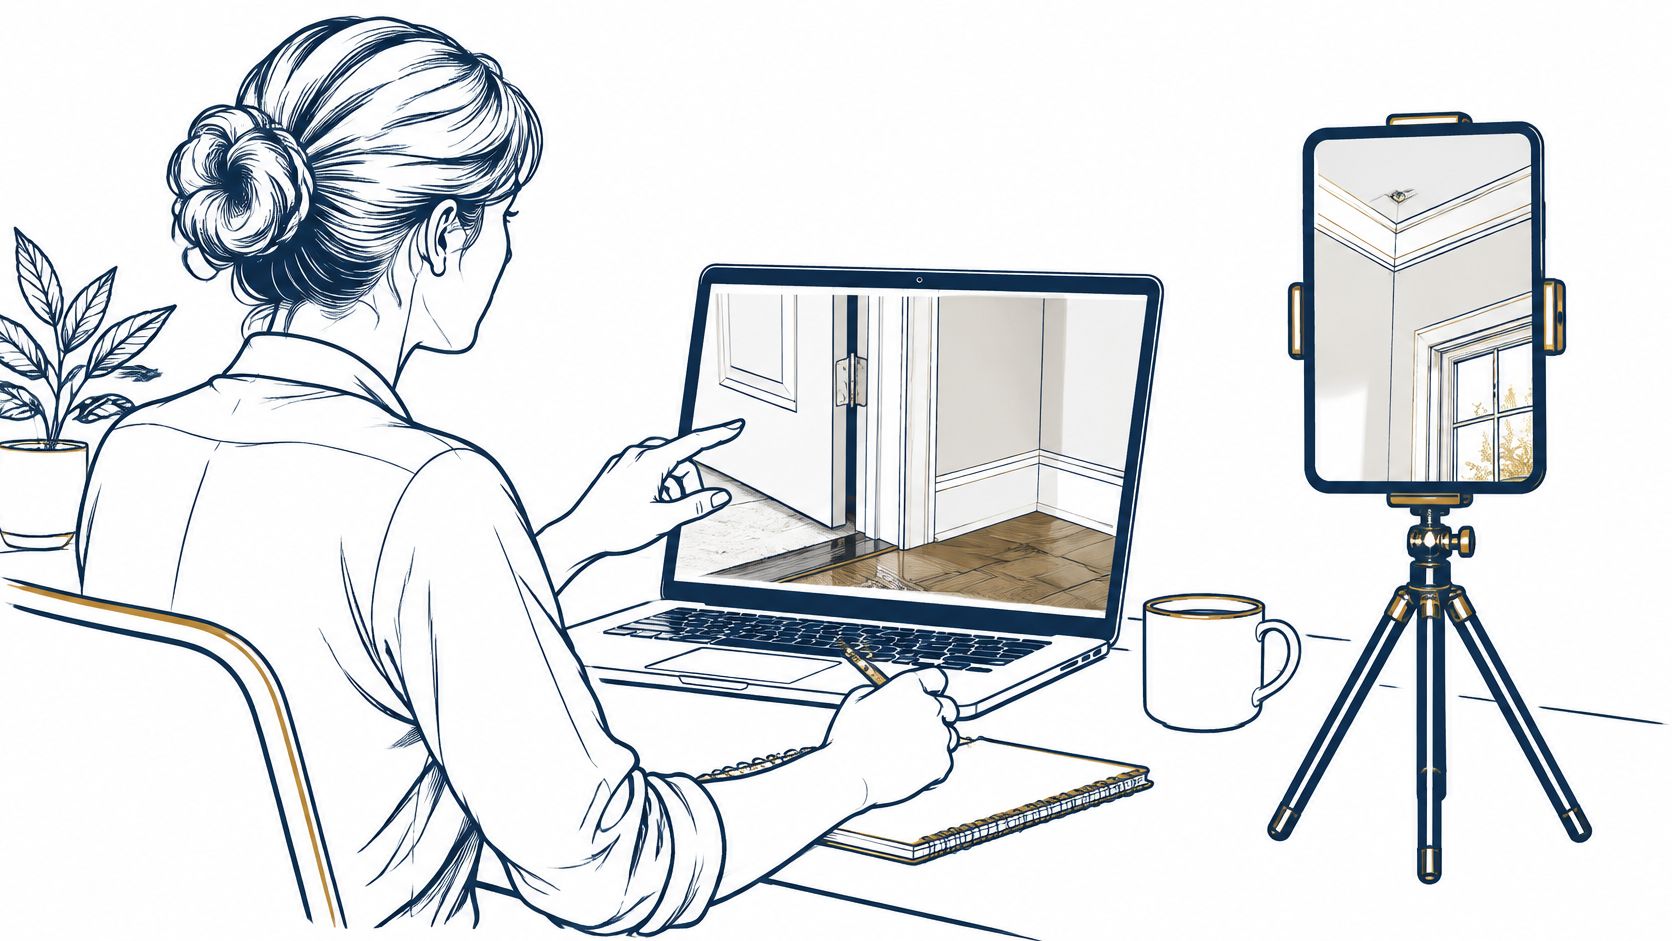
- Name the representative. A buyer's agent or trusted adult should conduct the call and report unfavorable findings plainly.
- Prepare a written checklist beforehand so attractive rooms don't distract from unresolved questions.
- Require live, unedited video. Move room by room, allowing the buyer to interrupt and request another angle.
- Cover ceilings, floors, windows, mechanical equipment, service panels, plumbing fixtures, exterior drainage, storage and bedroom views. Don't open electrical equipment or enter hazardous areas.
- Request timestamped close-ups of staining, damage and uneven surfaces so the inspector can investigate specific concerns.
- Compare room dimensions with a measured plan and reconcile included appliances, fixtures and equipment with the proposed contract.
The National Association of Realtors' virtual-showing resource page collects articles on remote tours, including one on avoiding liability in sight-unseen sales. Wide-angle lenses and selective camera paths can distort proportions or leave problem areas unseen.
Sound transmitted through a phone also isn't a dependable measure of actual noise, vibration or surrounding activity. The representative should describe those observations separately.
Practical rule: A clean video is a reason to order an inspection, not a reason to skip one.
Order Inspections, Appraisal and Wind Mitigation
An inspection evaluates condition; an appraisal addresses value. The Consumer Financial Protection Bureau explains that the lender generally requires an appraisal when financing is used and must provide the completed appraisal promptly. Arrange an independent home inspection once the property is selected, with access and timing coordinated around the contract.
Florida's Office of Insurance Regulation wind-mitigation resources identify Form OIR-B1-1802, the Uniform Mitigation Verification Inspection Form, and direct consumers to verify inspector authorization under Florida Statute 627.711(2)(a). Confirm an active, verifiable professional license before ordering; unverifiable credentials can prevent acceptance.
The wind inspection can document roof construction, roof-to-wall connections, doors, windows, skylights, garage doors, storm shutters or panels, and attic features. Name an adult representative beforehand and confirm attic access with the seller or manager.
| Verification | Who performs it | What it establishes | What it cannot establish |
|---|---|---|---|
| Independent home inspection | Licensed inspector hired by the buyer | Observable condition, defects and maintenance concerns | Concealed or inaccessible conditions |
| Lender appraisal | Appraiser engaged for the lender | Value for collateral analysis | A comprehensive defect assessment |
| Wind mitigation inspection | Authorized inspector with verifiable credentials | Mitigation features documented on the form | Future storm performance or insurer pricing |
| Specialist evaluation | Qualified system specialist | Condition within the specialist's scope | Repair cost or replacement timing unless expressly evaluated |
Request same-day video of defects and documentation of inaccessible areas. Roof, HVAC, structure, seawall, pool or septic evaluations should follow the property's systems and unresolved findings. The Gulf-front condo buying checklist helps organize building-level questions alongside the unit inspection.
Review Records and Track Contract Deadlines
Request the seller disclosure, prior insurance claims information, permits, alteration invoices, association documents, survey, tax records and title commitment. For a condo or planned community, expand the association request to cover inspections, reserves, rental rules and the building's insurance. Each record answers a different question; none substitutes for an inspection.
The Florida Office of Insurance Regulation's flood-insurance guidance explains that standard homeowners policies generally exclude flood damage, which makes prior claims information a records question rather than something a walkthrough can answer.
Compare records with visible conditions. An addition without a matching permit record needs investigation; a roof without an invoice needs supporting evidence, not an assumed installation date. The same test applies to a building's paperwork: reserve balances should match the repairs its inspection reports describe.
Match each open issue to a deadline
- Condition and insurability: Track inspection and insurance review dates, including time for specialist findings.
- Financing and value: Record financing and appraisal deadlines separately.
- Ownership and documents: Track title objections and association-document review under the signed agreement.
Confirm every date, notice method and responsible person with the representative. The signed contract controls; a calendar reminder doesn't extend a right. Arrange delivery of any required written objection before its deadline and retain confirmation. A missed date costs the buyer the right it was meant to protect.
For buyers also weighing making offers on under-contract homes, property status and contractual review rights remain separate questions.
Handle Local Logistics From Out of Area
Collect stored storm shutters or panels, roofing permits, invoices, product specifications and relevant maintenance logs before inspection day. Ask the seller or property manager to confirm attic access and any necessary entry codes.
Citizens' wind-inspection guidance says an owner who can't attend may designate a representative at least 18 years old. That representative should know where attic access, shutters and panels are located; certain mitigation features require attic access for verification.
Assign responsibility before closing
The representative and title company should confirm which utilities remain in the seller's name and how transfers will be coordinated. They should also establish who holds keys, remotes, gate credentials and access codes, and which codes will change.
Buyers working with Brian Burgett, Broker/Owner should clarify who will attend the final walkthrough. That person should verify agreed repairs, included items and consistency with the earlier walkthrough notes.
Record discrepancies before signing closing documents. A scheduled closing isn't evidence that an unresolved repair was completed.
Confirm arrangements directly with the parties involved rather than relying on assumed inspection or transfer timing.
Decide Whether the Remote Purchase Passes Your Checks
Proceed only when the evidence supports the next commitment. Before an offer, resolve missing mapping, quotes and material association information. Before signing, confirm the required disclosure and understand the proposed contract protections.
An inaccessible area is an unresolved question, not a satisfactory inspection result. Before the applicable review period ends, decide whether to seek access, commission further evaluation, negotiate a documented response or exercise an available cancellation right.
Unexplained alterations and conflicting records deserve written questions and timely contractual notices. If a deadline has passed, the representative and, where needed, an attorney should review the agreement before the buyer assumes cancellation remains available.
Buying a house sight unseen is a verification decision, not a technology decision. Better video can't compensate for missing evidence or expired review rights.
Dream Destin Realty provides live listings and local market information for Emerald Coast purchase planning. Visit Dream Destin Realty to explore those resources, then contact the brokerage with the property address and unresolved remote-purchase questions.


